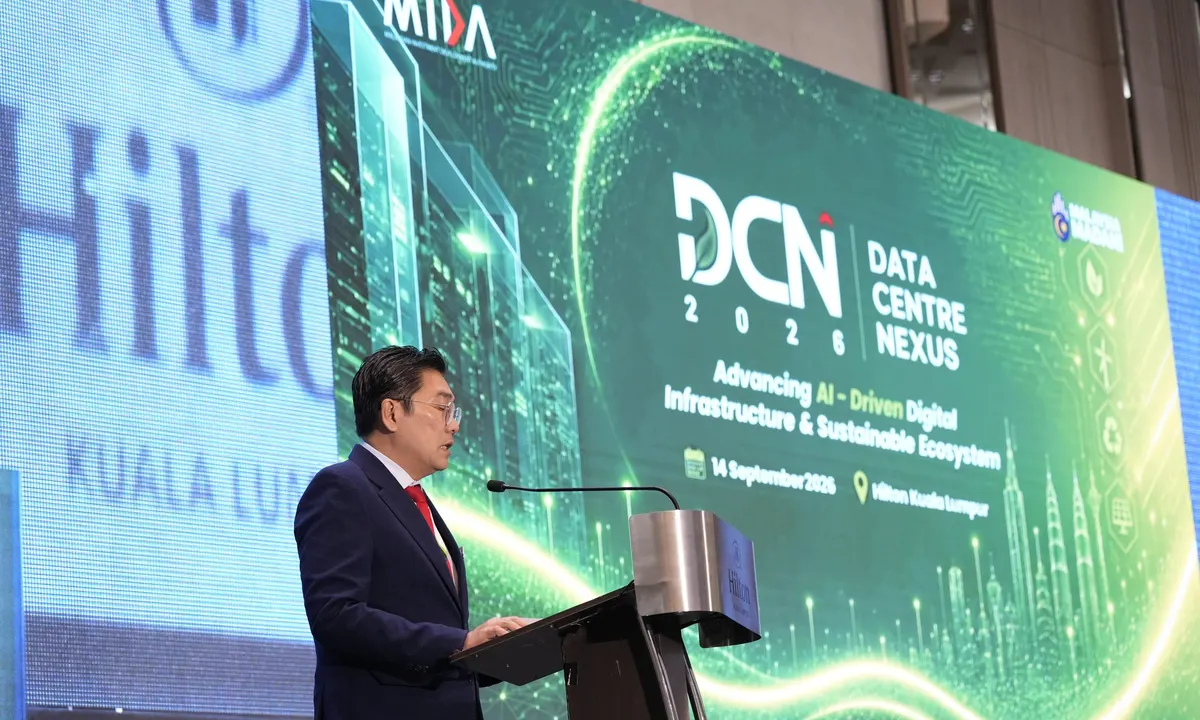
The Malaysian Investment Development Authority is pushing the country’s data-centre strategy beyond investment attraction and towards local value creation. At Data Centre Nexus 2026 in Kuala Lumpur, the agency said Malaysia had recorded RM385.7 billion in data-centre-related investment from 2021 through the first half of 2026, giving the sector enough scale for policy attention to turn to suppliers, skills and operating impact.
What is moving
The agency’s business-matching programme brought together 14 data-centre companies and 51 Malaysian vendors. MIDA said the previous year involved eight data-centre companies and 17 local vendors. The larger participation provides a measurable sign of supplier interest, although attendance at a matching session does not establish that contracts were signed or that local companies have entered operators’ approved supply chains.
MIDA framed the next phase around four areas: artificial-intelligence infrastructure, resource efficiency and sustainability, local ecosystem spillovers, and wider digital access. The combination matters because data-centre investment can add construction and service demand while still importing much of its specialist equipment. Local value depends on which engineering, maintenance, energy, security and technology functions Malaysian firms can supply competitively.
What remains open
The resource question is becoming more material as the sector expands. MIDA cited a projection that electricity demand from data centres could exceed 5,000 megawatts by 2035. That figure is a forward estimate, not current consumption. It nevertheless increases the importance of grid planning, renewable supply, water management and efficiency requirements when new capacity is evaluated.
Why it matters
For Malaysian small and medium-sized enterprises, the business opportunity is more specific than the investment headline. Operators require reliable contractors, cooling and electrical expertise, compliance support, cybersecurity, facility management and increasingly specialised software. Qualification standards, reference projects and the ability to serve large campuses will determine which local companies can turn introductions into recurring work.
The named global operators in MIDA’s account include Amazon Web Services, Microsoft, Google, Bridge Data Centres, DayOne, AirTrunk and Vantage. Their presence signals demand for a deeper service base, but it does not mean each company made a new commitment at the event. Project status, capacity and procurement remain specific to each operator and site.
Malaysia’s policy challenge is therefore moving from volume to composition. Large capital commitments can support jobs and infrastructure, yet the durable benefit depends on local technical roles, supplier contracts, skills transfer and services that remain in the economy after construction. MIDA’s programme establishes those outcomes as priorities without quantifying how much of the RM385.7 billion will be captured locally.
The practical indicators will be vendor qualification, awarded packages, workforce development and resource performance. Those measures would show whether the sector is creating operating capability alongside physical capacity. They would also help investors and communities compare the economic return with the power, land and water required by each development.
MIDA’s latest statement is best read as a policy and market signal rather than a new project award. Malaysia has already attracted a substantial pipeline. The next stage is to make the supplier ecosystem and infrastructure obligations visible enough for businesses to judge where genuine participation is emerging.
Source note
SEA Connect based this report on MIDA’s 14 September media release for Data Centre Nexus 2026. Investment, participation and electricity-demand figures are attributed to the agency; the release did not disclose new individual project awards or vendor contracts.